


Most investors treat the Fed's next rate call as a simple question: cut, hold, or hike. This month that question has a complication sitting underneath it. The government shutdown that began on 1 October has now run three weeks, and it has switched off a good part of the data the Fed normally reads before it moves. In seven days the committee has to decide anyway. That's why we built Winvesta Crisps, to break down what's actually moving markets, in plain language, before the consensus catches up. 60,000+ investors from all over India are already in. What about you?
🔔 Don't miss out! Add winvestacrisps@substack.com to your email list so our updates never land in spam.
On 1 October, Congress failed to pass a funding bill and the federal government shut down for the second time in under a year. Three weeks on, it is still shut, Washington is no closer to a deal than it was in week one, and the Federal Open Market Committee meets on 28 October to decide what happens to the policy rate that sets the cost of money for every dollar asset an Indian investor holds. The twist is not whether the Fed wants to cut again. This newsletter noted on 6 October that a third cut in 2026 was all but priced in. The twist is that the agencies that normally hand the Fed its evidence, on jobs, on prices, on spending, have mostly stopped producing it, and the committee has to make the call with a meaningfully thinner file than usual.
🏛️ What a shutdown actually switches off
A government shutdown is not a metaphor. When Congress does not pass appropriations bills or a continuing resolution by the start of the new fiscal year, federal agencies lose their legal authority to spend money, full stop. Non-essential staff are furloughed, essential staff keep working without pay until it ends, and anything that depends on a federal agency publishing something on schedule simply stops showing up.
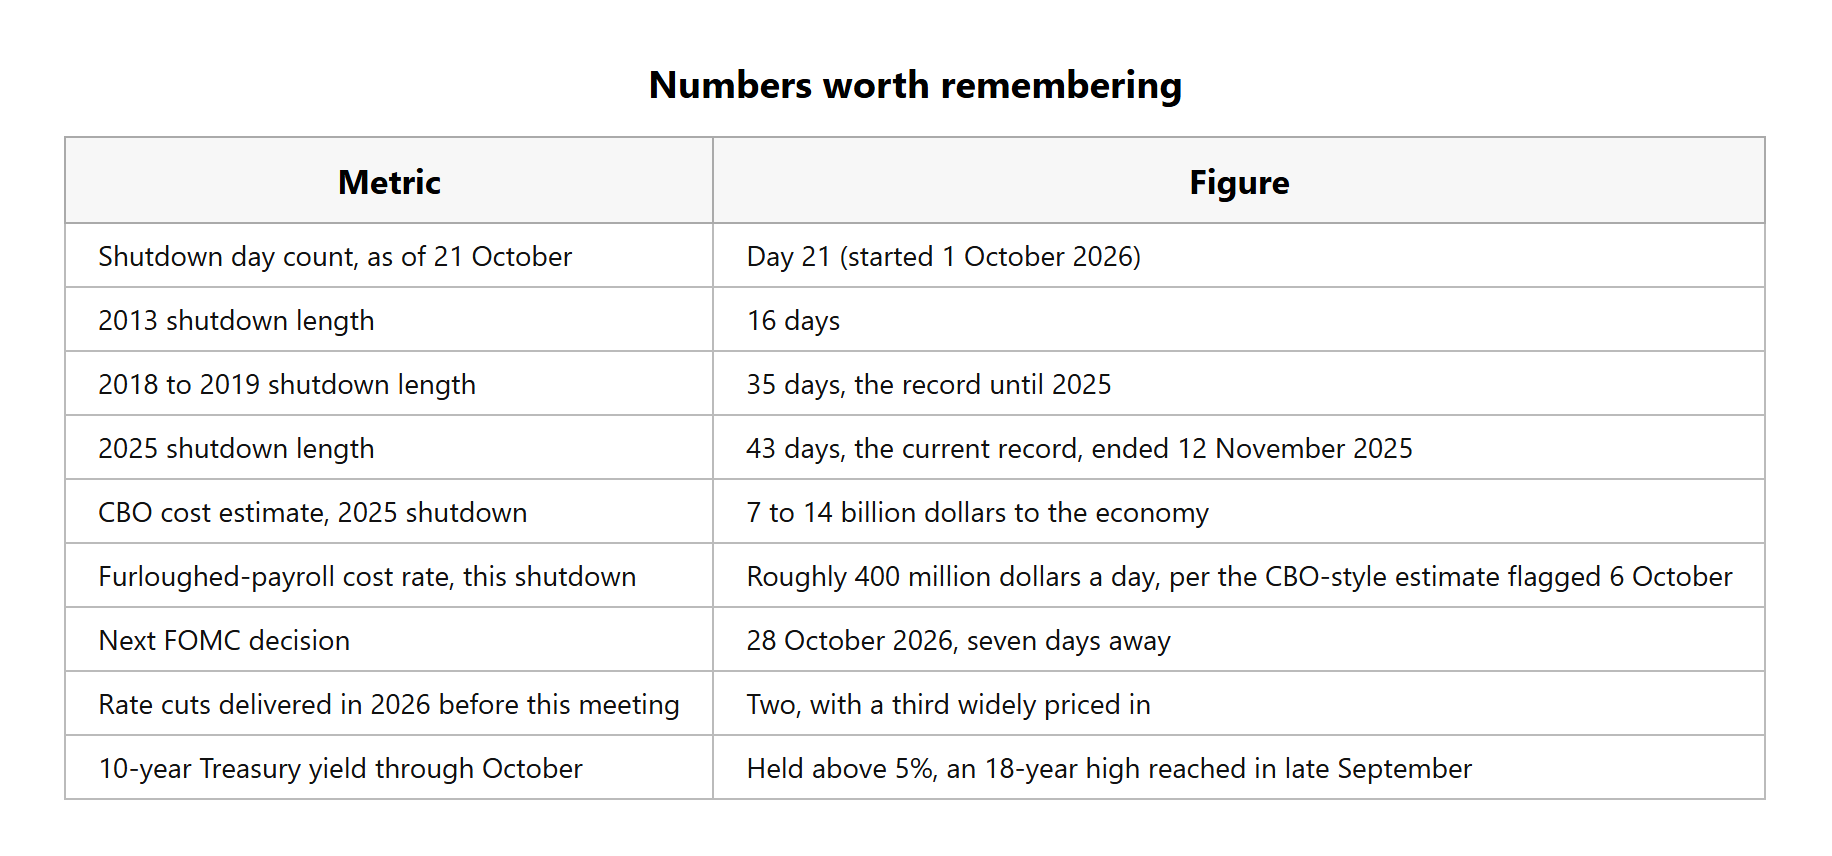
This is not a one-off event. The 2013 shutdown ran 16 days. The 2018 to 2019 shutdown ran 35 days and was, at the time, the longest in US history. Last year's shutdown broke that record outright: it ran 43 days, from 1 October to 12 November 2025, and the Congressional Budget Office put its cost to the economy at 7 to 14 billion dollars, with fourth-quarter annualised GDP growth cut by an estimated 1 to 2 percentage points and the unemployment rate pushed up by roughly 0.4 percentage points. None of that was recovered quickly. A chunk of it, the CBO said, would never be recovered at all.
What makes this year's repeat unusual is not its length so far, three weeks is still short by last year's standard, but its timing. It has landed directly on top of a Fed meeting, for the second time in two cycles, at a moment when the central bank's own credibility is already under the kind of scrutiny this newsletter covered through September's rate hike debate and the Jackson Hole speech that preceded it.
⚙️ How the Fed is supposed to decide, and what happens when half the inputs go dark
The Fed's rate decisions run on a handful of government data series: the monthly jobs report from the Bureau of Labor Statistics, the consumer price index, GDP from the Bureau of Economic Analysis, retail sales from the Census Bureau. During a shutdown, the statistical agencies that produce these numbers stop collecting and publishing them, because that work itself is federal spending that has just lost its authorisation.
The precedent from last year's 43-day shutdown is direct. The BLS delayed its September 2025 jobs report by roughly seven weeks, to 20 November, and said it could not calculate a full October unemployment rate at all because the household survey that feeds it cannot be conducted retroactively once the window for it has closed. The Fed still had a rate decision to make in that window, and it cut anyway, in what reporting at the time described as the first occasion the committee had made a call without the government data it would normally lean on. Chicago Fed president Austan Goolsbee said plainly that the committee would use outside data where the official numbers were missing.
That is exactly the position the FOMC is in again. In place of BLS and Census numbers, the committee leans on private substitutes: ADP's payroll data, which draws on the roughly 25 million workers on its own payroll platform and keeps publishing through a lapse; ISM manufacturing and services surveys; card-spending trackers from Visa and Mastercard; regional Fed surveys; and scheduling data from platforms like Homebase that proxy for small-business hiring. Every one of these is noisier and narrower than the official series it stands in for. None of them covers the full economy the way a BLS household survey does. The Fed is not flying with no instruments. It is flying with a smaller panel of instruments, each individually less reliable, at the exact moment a policy mistake in either direction (cutting into stickier inflation than the committee realises, or holding into a labour market that is weakening faster than the private data shows) is harder to catch and reverse quickly.
The dynamics covered in this article affect every US stock in your portfolio. Trade from India on the Winvesta app. No US bank account needed!
🚀 Join 60,000+ investors, become a paying subscriber or download the Winvesta app and fund your account to get insights like this for free!
🏆 Who the data blackout actually hurts and helps
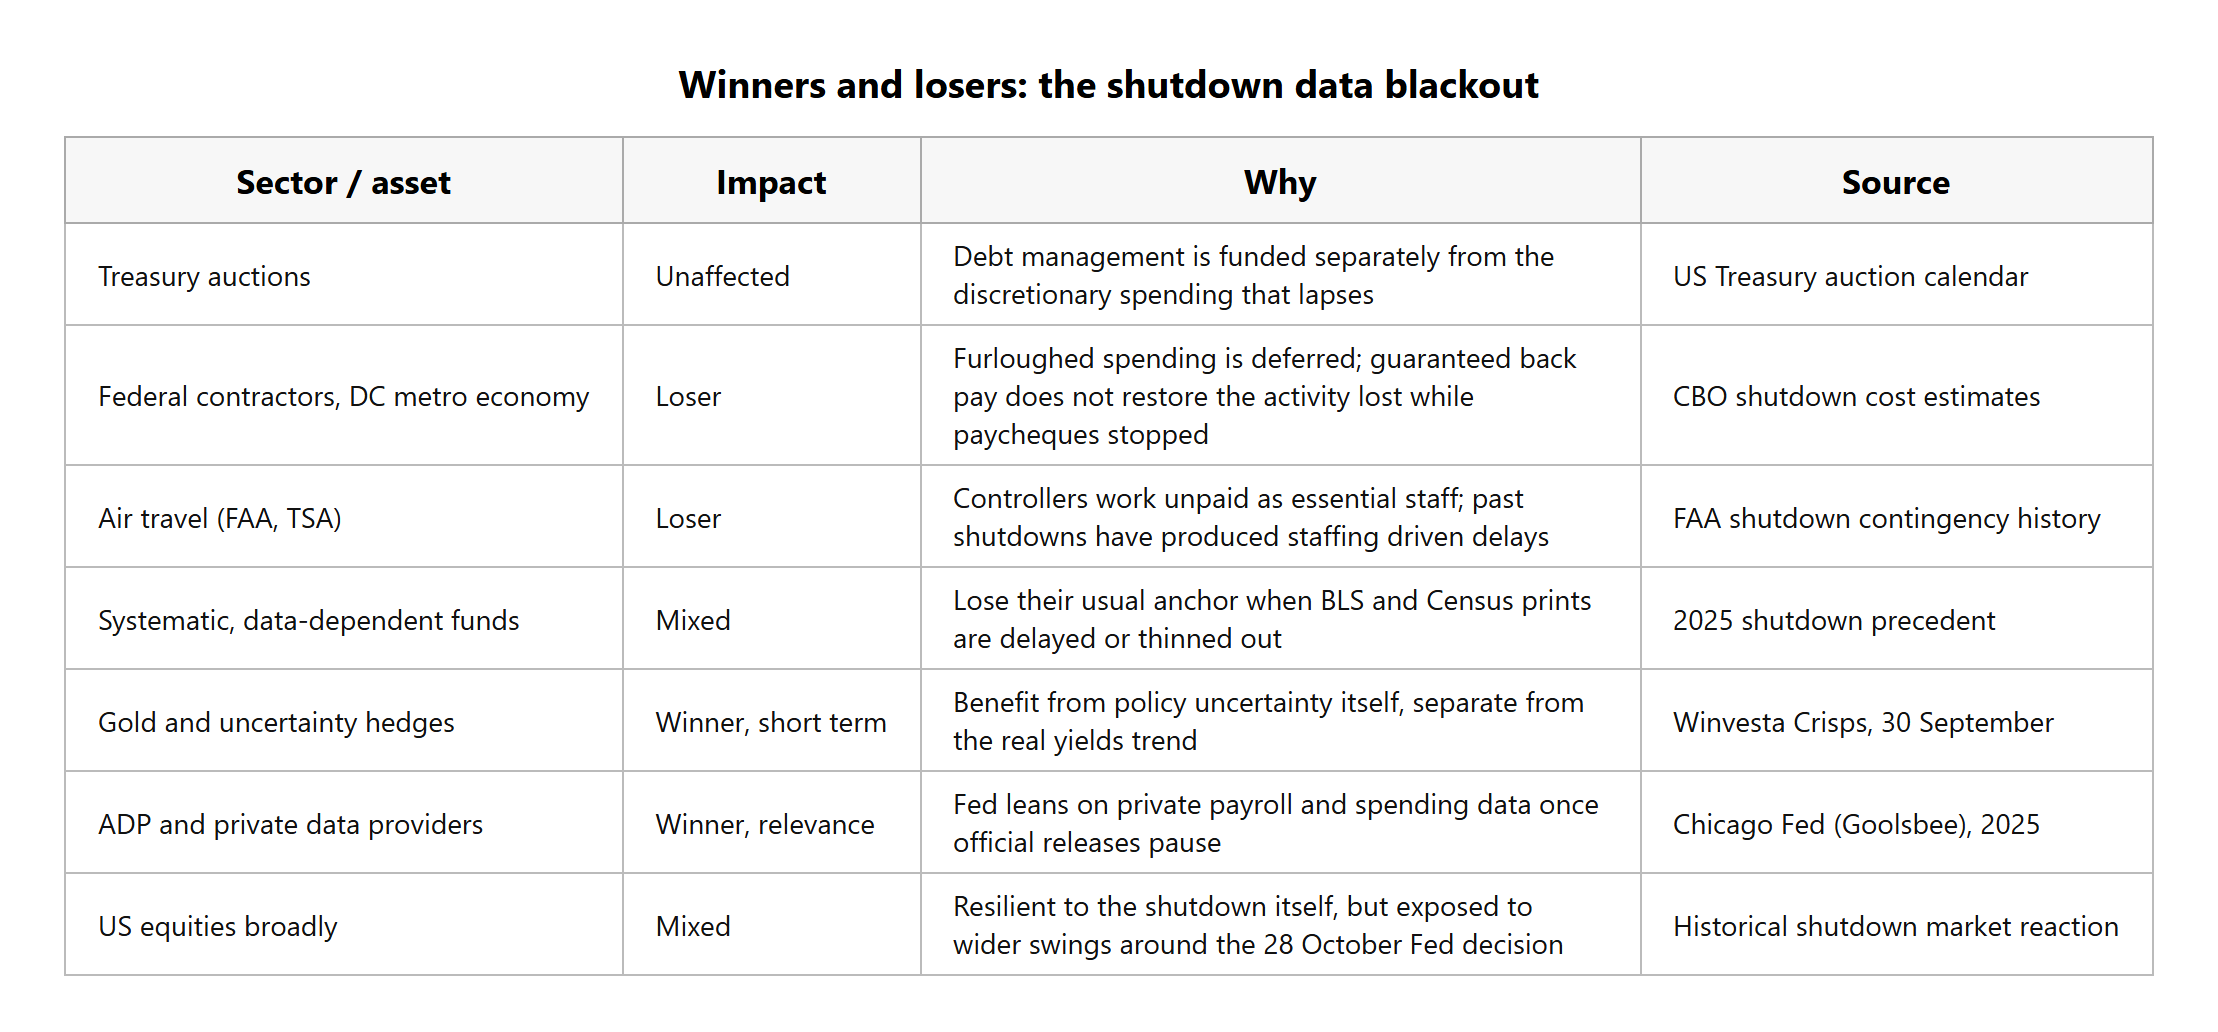
Treasury markets, oddly, are among the least affected in the short run. Auctions continue on schedule because Treasury debt management is funded separately from the discretionary spending that lapses, so the long end's own deficit-and-issuance story, the one driving the 10-year yield above 5% through October, keeps running on its own logic regardless of whether BLS is open.
Federal contractors and the local economies built around them are the clearest losers. The Washington DC metro area alone carries hundreds of thousands of federal and federally-dependent jobs, and furloughed back pay, guaranteed since 2019 legislation, does not restore spending that households deferred while their paycheques stopped. Airlines and air travel sit in the same bucket: air traffic controllers are classed essential and keep working unpaid, and past shutdowns have produced exactly the kind of staffing-driven delays and flight cuts that eventually force the FAA's hand.
Systematic and data-dependent funds sit in the uncomfortable middle. Strategies built around the monthly jobs print or CPI release lose their anchor entirely when those prints are delayed or thinned out, which tends to show up as choppier, less predictable trading around the dates those releases would otherwise have landed.
Gold and other instruments that benefit from uncertainty rather than from any specific data point are the clearest beneficiaries, for as long as the uncertainty lasts. That is a separate mechanism from the real-yields story this newsletter walked through on 30 September, and the two can point in opposite directions at once, which is part of why gold has traded choppily rather than in a clean trend through this stretch.
🌏 What this means if you are investing from India
An Indian investor holding US equities through the Winvesta app does not get a pass on any of this because the shutdown is a domestic American political story. The FOMC's decision on 28 October lands in every dollar-denominated holding regardless of where the investor sits, and a data blackout does not mean lower uncertainty around that decision. It means the opposite: wider bands around what the Fed might do, and historically, wider bands around how markets react once the decision actually lands.
The currency leg matters just as much. If the Fed cuts again on thinner evidence, a softer dollar is the more likely near-term reaction, which works in favour of unhedged dollar asset holders translating gains back into rupees. If the committee instead holds, judging the private data too unreliable to act on, the dollar's recent strength has more room to persist, which is the same pressure this newsletter detailed on 9 September, when the RBI had already spent an estimated 136 billion dollars defending the rupee this year. A shutdown that drags past 28 October without resolution raises the odds of that second scenario, because a Fed genuinely uncertain about the state of the economy has more reason to wait for clarity than to act on it.
The practical read-through is not to guess which way the Fed goes. It is to expect a noisier few days around 28 October than a normal meeting would produce, and to size any short-term trading around that date accordingly rather than treating a data vacuum as a quiet one.
If this changed how you read the next Fed decision, pass it on.
📊 The bottom line
A government shutdown does not just furlough federal workers. It furloughs the statistics the Fed needs to do its job properly, at precisely the moment the job gets harder to do well. The central bank has shown, in last year's 43-day shutdown, that it will make the call anyway rather than wait indefinitely, leaning on a thinner, noisier set of private substitutes for the official data it would rather have. That is not a reason to assume the Fed gets it wrong on 28 October. It is a reason to expect more uncertainty than usual around whichever call it makes, and to remember that uncertainty, not any specific number, is often the thing markets actually trade on.
📈 Numbers worth remembering
This article is for educational purposes only and does not constitute investment advice. Winvesta India Technologies Ltd. does not guarantee the accuracy of third-party data cited above. Past performance is not indicative of future returns. Please consult a registered financial adviser before making investment decisions.
The point about private substitutes deserves a closer look, because they fail in a specific way: ADP and card-spending data are built to track the official series, so they tend to inherit its blind spots rather than correct them. What may matter more on 28 October is market-based inference, with OIS pricing and credit spreads moving daily while the BLS is dark. I'd also ask whether a 10-year yield sitting above 5% is handing the committee a tightening signal it cannot observe anywhere else.