


Five years ago, the rule for owning energy or defense exposure was simple: wait for a headline crisis, buy the spike, sell the relief rally. That rule assumed the crisis would end in weeks. The Strait of Hormuz standoff is now well into its second month with no resolution in sight, and the funds tied to it are behaving like an income position, not a trade. That's why we built Winvesta Crisps, to decode what's actually moving the funds you own, in plain language, before the consensus catches up. 60,000+ investors from all over India are already in. What about you?
🔔 Don't miss out! Add winvestacrisps@substack.com to your email list so our updates never land in spam.
Most investors are watching the Strait of Hormuz standoff the way they watch any other headline war: as background noise for a portfolio that lives somewhere else. That assumption stopped being safe weeks ago. Brent crude closed near $107 a barrel on 28 September and West Texas Intermediate near $94, both up sharply from about $57 in January, after the latest round of US-Iran talks over reopening the strait broke down again and war-risk shipping insurance in the Red Sea reportedly tripled. The ten-year Treasury yield has climbed alongside it, closing near 5.01% on 16 September, its highest level since 2023, and pushing higher still through the back half of the month as the standoff dragged on with no resolution.
Two US sector funds have quietly done exactly what a war-and-oil-shock regime is supposed to do to them. The iShares US Aerospace & Defense fund, ticker ITA, is up 16.7% year to date. The Energy Select Sector SPDR, ticker XLE, is up close to 24%. The problem is almost nobody holding a standard US portfolio out of India owns either one.
🎯 Meet Neha
Neha is 34, a lead product manager at a Pune fintech, and has run a US portfolio since early 2023. It is worth roughly ₹56 lakh: a Nasdaq-100 index fund makes up just over half of it, and the rest sits in five megacap names she added one at a time whenever they came up in her company's internal trading Slack channel, Nvidia and Microsoft among them. She has never owned an energy fund, a defense fund, or a barrel of oil in any form. Her reasoning was straightforward: geopolitics is noise, technology is the sector that has actually made her money since 2021, and she does not have the bandwidth to trade headlines.
That reasoning survived three years of a market where the Fed was cutting, oil was cheap, and the ten-year yield sat comfortably under 4.5%. It has not survived this one.
Her question this week is specific. She has watched two funds she has never looked at twice, ITA and XLE, post some of the steadiest double-digit gains in the market this year, while the Nasdaq-100 fund that makes up more than half her portfolio has gone nowhere for six weeks. She wants to know if adding either fund now is chasing a headline that could reverse the day a ceasefire is announced, or catching a structural shift she has been on the wrong side of since January.
Her hidden exposure. Run the actual sector math on that Nasdaq-100 fund and the picture is starker than "some tech." Technology and communication-services names make up close to nine-tenths of the index by weight. Energy and industrials, the two sectors doing the work in XLE and ITA respectively, are close to a rounding error inside it. Neha does not hold a diversified portfolio that happens to be tech-heavy. She holds a single macro bet, dressed up as an index fund, with the two sectors best placed to hedge it at effectively zero weight.
What happened last time this regime showed up. 2022 is the closest precedent: the Fed hiking fast, oil elevated after Russia's invasion of Ukraine, and long-duration growth stocks getting hit hardest by higher discount rates. The Nasdaq Composite fell by roughly a third that year. The S&P energy sector was the only one of eleven S&P sectors to finish positive, up in the region of 60% to 65%. Neha was not investing yet in 2022. She has never lived through the version of this movie where her actual holdings are the ones losing.
📊 What these two funds actually own
Start with what her Nasdaq fund does not give her: real exposure to either the war-spending story or the oil-price story. Not because it is a bad fund, but because a fund that is nine-tenths technology and communication services by design carries no meaningful weight in defense contractors or energy producers, no matter how large it gets.
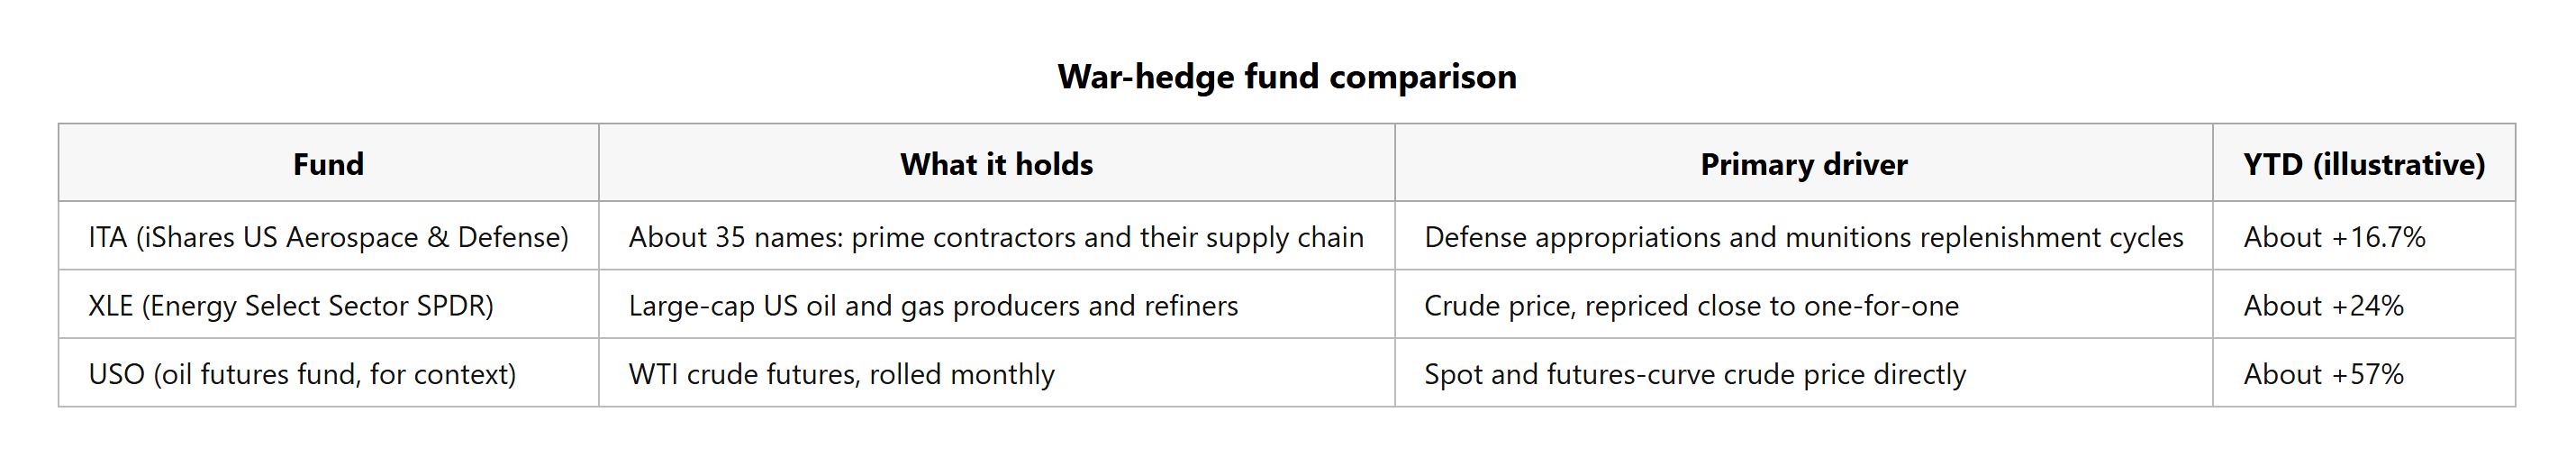
iShares' US Aerospace & Defense fund, ITA, holds around three dozen names concentrated in prime contractors and their supply chain, Boeing, Lockheed Martin and RTX among the largest. Its return this year is driven less by the day-to-day oil price than by a slower, stickier mechanism: emergency defense appropriations and munitions replenishment orders that, once placed, tend to run for years rather than weeks. Patriot interceptor costs alone reportedly topped $3.2 billion in the first week of the current conflict, and total defense spending tied to it has been estimated at roughly $1 billion a day. None of that reverses the day a ceasefire is signed.
The Energy Select Sector SPDR, XLE, is the more direct trade: large-cap oil and gas producers and refiners whose earnings move close to one-for-one with the crude price. It is up roughly 24% year to date, behind the oil-futures fund USO's steeper gain of around 57%, because XLE's largest holdings hedge part of their own production and USO does not. XLE is also the fund that would give back the most, the fastest, on a genuine de-escalation headline.