Five years ago, analysing Adobe meant counting Creative Cloud seats and checking whether the annual price rise had stuck. Not anymore. Adobe now touches more than a billion people a month, has built an AI business growing at triple digits, and is handing the chief executive's job to an IIT Varanasi graduate on 1 December. The market has responded by pricing the whole company at roughly nine times next year's earnings, which is what software trades at when investors think it is about to be replaced. That's why we built Winvesta Crisps, to decode what's actually driving the companies you own, in plain language, before the consensus catches up. 60,000+ investors from all over India are already in. What about you?
🔔 Don't miss out!
Add winvestacrisps@substack.com to your email list so our updates never land in spam.
Most investors still think of Adobe as the company that rents Photoshop to designers. That framing is accurate and dangerously incomplete. On 10 September Adobe reported quarterly revenue of $6.76 billion, up 13% year-over-year, with non-GAAP operating margin running near 45% and annualised recurring revenue of $27.50 billion, per Adobe's Q3 FY2026 earnings release. On the same call, management said monthly active users across the business had passed one billion for the first time. The stock fell. It closed at $250.50 on 16 September, down about 28% over twelve months, on a forward price to earnings multiple of roughly 9.3 times, per market data. There are two ways to read a set of numbers like that. Either the market has stopped believing the earnings are durable, or it has stopped reading. This article is about which.
🏭 What Adobe actually is today
Start with a change most investors have not registered. Through fiscal 2025, Adobe reported itself as two segments: Digital Media, $17.65 billion of revenue in FY2025, and Digital Experience, $5.86 billion, up 9%, per the Q4 FY2025 release. From fiscal 2026 the company reports by customer group instead. The old map no longer matches the territory, and if you are still modelling Adobe as "Creative Cloud plus a marketing software business bolted on", you are working from a retired chart.
The first group is creative and marketing professionals. This is the business people picture: Photoshop, Illustrator, Premiere, After Effects, plus the enterprise marketing stack of Experience Manager, Experience Platform and GenStudio. It produced $4.65 billion of subscription revenue in the quarter, up 13% year-over-year, per the Q3 FY2026 release. Within it, management said Experience Manager, GenStudio and Experience Platform each grew ending ARR by more than 20%, which is the part of Adobe that competes with Salesforce rather than with Canva.
The second group is business professionals and consumers. Acrobat and Adobe Express, sold to accountants, lawyers, sales teams, students and anyone who has ever needed to sign a PDF. Subscription revenue of $1.91 billion, up 16% year-over-year, making it the faster-growing half. Management put monthly active users for this group above 900 million, up more than 25%. That is not a design tool business. It is a distribution business with the reach of a consumer internet company, sitting inside a firm the market still values as enterprise software.
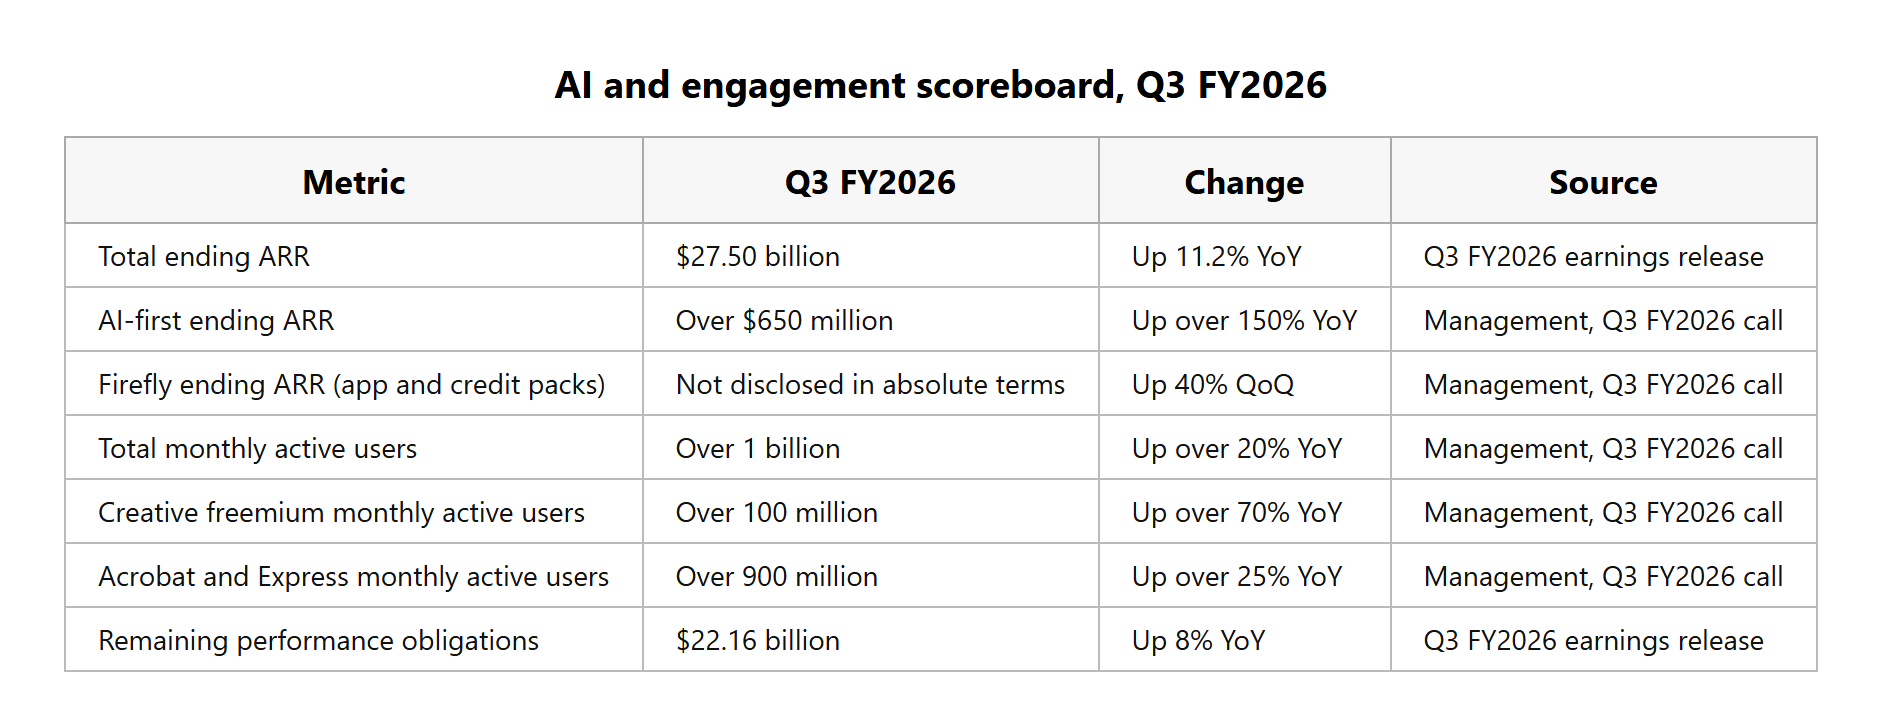
The third thing is not a segment, it is a layer that cuts across both. Firefly for image, video, audio and speech generation; AI Assistant inside Acrobat; agentic features moving through the enterprise products. Adobe reports the money this earns as AI-first ending ARR, and said it exceeded $650 million in the quarter, growing more than 150% year-over-year. Hold that number. It decides the argument.
Put the three together and Adobe is a very profitable professional software company that has quietly acquired a consumer-scale audience, and is now trying to charge a fraction of that audience for AI features before somebody gives those features away free. The first half of that sentence is finished and proven. The second half is entirely unresolved, which is precisely why the shares trade where they do.
🧩 Segment breakdown
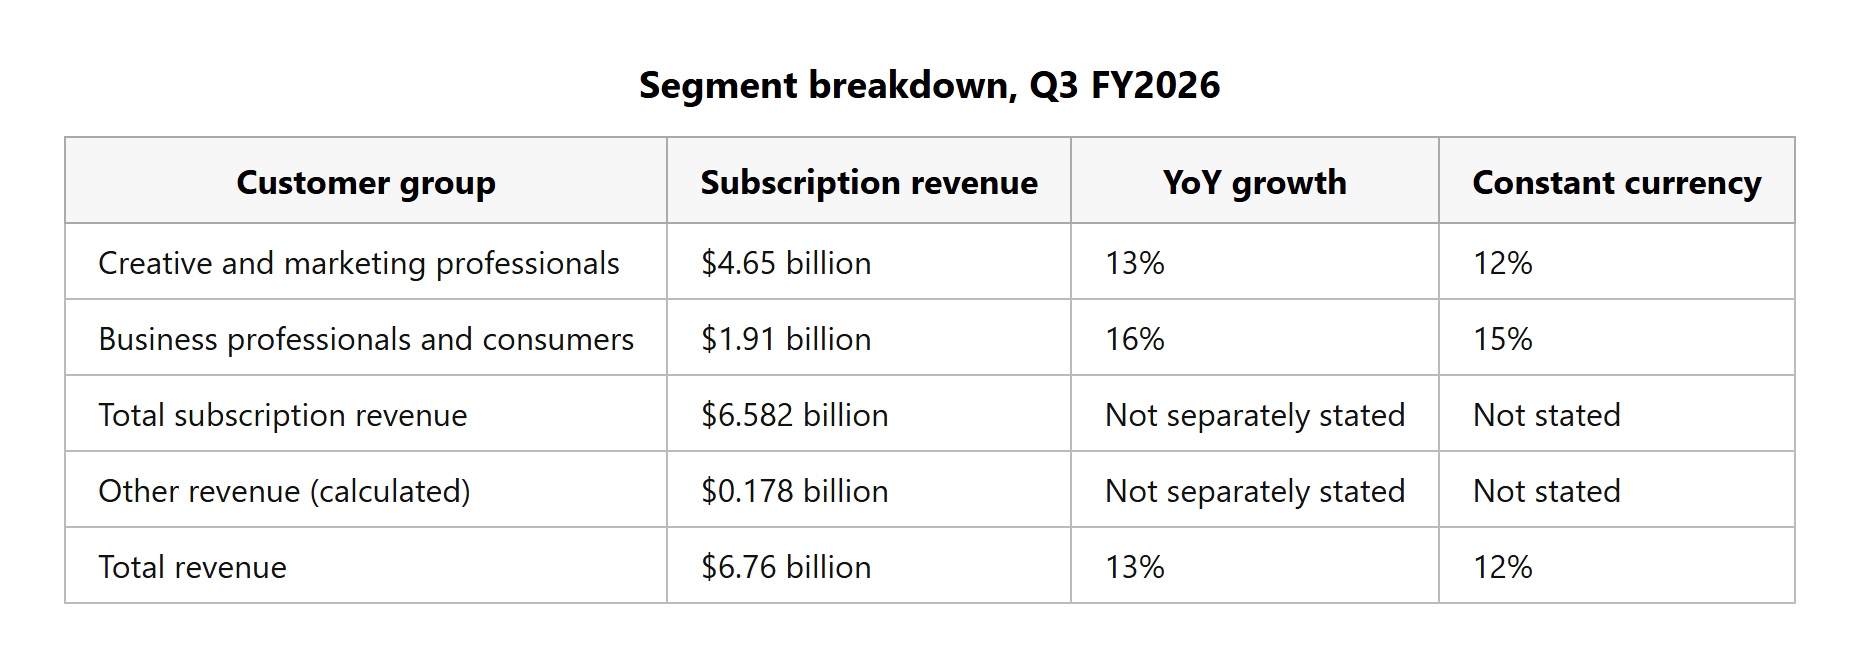
Two observations. Subscription revenue is $6.582 billion of $6.76 billion, so about 97% of Adobe's revenue recurs. Very few companies of this size have that mix, and it is the reason the operating margin sits where it does.
The other observation is about the residual. The two customer groups together account for $6.56 billion, leaving roughly $178 million of other revenue, which the headline release does not break out separately in the same summary. The figure shown here is arithmetic from the reported totals rather than a printed Adobe line item, and should be read that way.
⚡ The core strategic bet: one billion users, and the conversion question
Adobe's strategy has changed in a way the segment table cannot show. For twenty years the company sold a licence, raised the price, and counted seats. The new plan is to put free or near-free AI tools in front of as many people as possible, measure what they do, and convert the engaged ones later.
The evidence that the first half is working is unusually clear. Total monthly active users passed one billion, up more than 20% year-over-year. Creative freemium monthly active users crossed 100 million, up more than 70%. Acrobat AI Assistant monthly active users doubled quarter-on-quarter, per management commentary on the Q3 FY2026 call.
Now put that beside the money. Total ending ARR is $27.50 billion, growing 11.2%. AI-first ending ARR is just over $650 million. So the AI business, after all the noise of the last three years, is about 2.4% of what Adobe collects, on our own arithmetic from the two disclosed figures. Divide total ARR by total monthly users and Adobe earns roughly $27 a year per monthly active user across the base, which for a company whose flagship subscription costs several hundred dollars a year tells you how little of the billion is paying anything at all.